
9/14/2026

Good morning, after the dry, dusty and downright sweltering summer, Europe appears to be imitating a subtropical island in wet season, which is just as well since it’s raining ABS.
No fewer than eight deals were priced across euros and sterling last week, in what the Concept ABS team believes is the busiest week (for ex-CLO offered trades) since the company began way back in 2007. And there looks to be no sign of respite either with nine more already in the pipeline.
It was also pleasing to see the week’s action have a healthy amount of sterling interest. It has at times felt like an afterthought, such has been the strength of euro-denominated issuance, particularly across Autos and Consumer ABS.
Investors in both regions are clearly well engaged, it is September after all. But that did not mean issuers had it all their own way.
Newcastle Building Society’s second ever Prime RMBS, the £383m Hadrian Funding 2026-1, was unable to break the stubborn 55bps over Sonia floor that appeared a few months ago in UK Prime. Early on in the year, deals were getting below 50bps.
Similarly in the Netherlands, Domivest’s BTL RMBS, the €478.4m Domi 2026-2 priced its triple-A’s 4bps wide of the January Domi 2026-1 at 68bps over 3-month Euribor. With the leads unable to push any tighter, they instead settled for a last minute upsize.
Finally, Volkswagen – having just printed its third German auto the week before – priced its UK version, the £417.5m Driver UK Twelve. However, the triple-A’s were priced at 70bps over Sonia, a whopping 11bps wide of BMW’s Bavarian Sky back in June and 12bps wide of Driver 11 from February.
It was clearly a difficult result, synonymous with Volkswagen’s broader difficult year – its share price is down about a third YTD and thousands of job cuts have been announced. Yet it is probably complacent to pin this all on the vagaries of VW’s own issues.
There are bigger issues at play too. Government bond yields are rising – the UK’s 10-Year Gilt for example is at 5.2%, now just a few bps away from highs last seen in 2007. There’s war in Iran, while the war in Ukraine looks to be intensifying. And there are various concerns about the huge lending needed to support the AI tech boom.
And of course, in European ABS there’s an awful lot of supply – and that’s probably the biggest factor in all this.
Our conversations have been clear – accounts are engaged. But the balance of power is shifting. With so much to choose from investors are not going to be taken for a ride as they desperately try to put their capital to work.
In fairness, they are also being more explicit with what they will and won’t do – a welcome change in the eyes of many bankers.
It’s easy to put a negative spin on spread widening, to think that it’s a sign the market will soon shut up shop (in part because not so long ago that’s normally what happened). But in this case, we should remember the context.
As the graph below show, according to Concept ABS data, since 2024 issuers have been able to essentially pay what they want, across the stack.
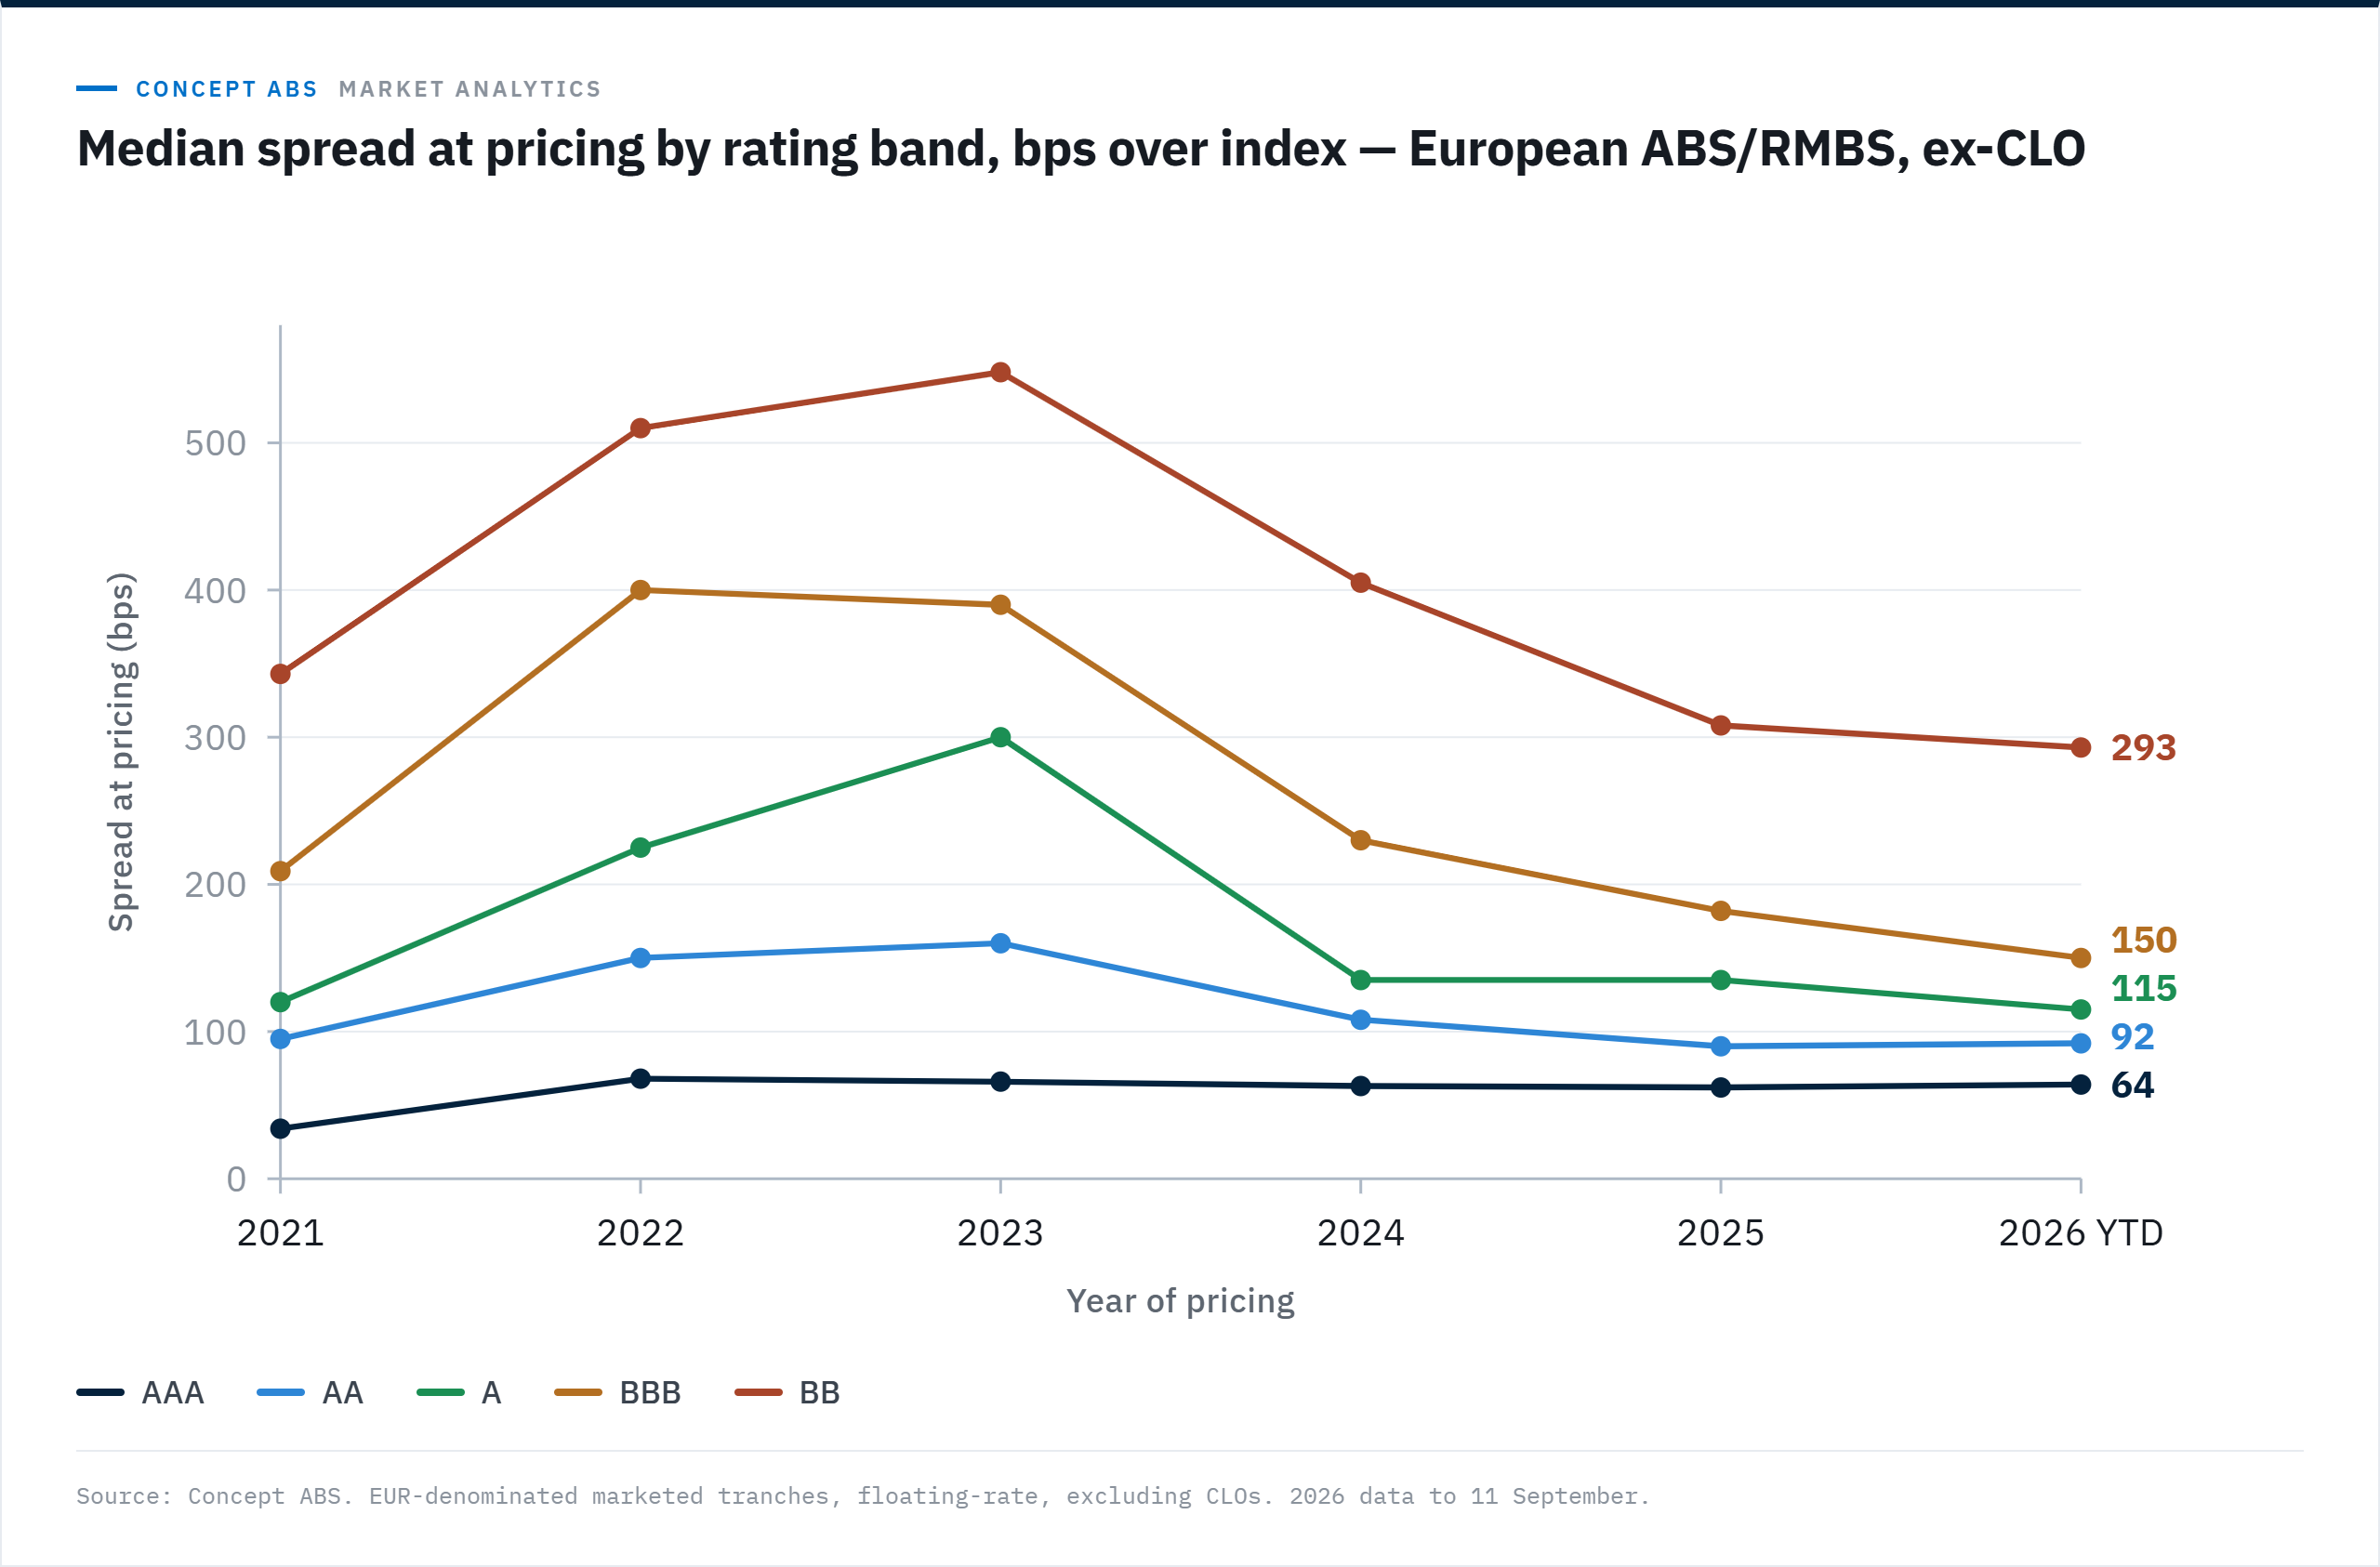
It’s bordering on ridiculous really. To dominate proceedings like this for so long. For how long have we seen IPTs start way wide only to scream tighter like clockwork?
They say variety is the spice of life. Perhaps this is the end of the multi-year “seller’s market” and perhaps that’s no bad thing?
Ubiquitous auto and consumer loan originator Santander Consumer has bought Italian auto collateral for the second time this year, the latest Golden Bar deal offering a full capital structure – albeit with pre-placement originally mooted at the top of the stack. This is the first time the Golden Bar brand has fully marketed auto paper (as opposed to consumer loans) since 2019 – an appropriate milestone given just how ubiquitous auto product has been in the early post summer days...click here to read the full overview on Concept ABS.
The post-summer market reopening continues to gather pace, with Santander Consumer bringing the fifth euro-denominated auto deal since the reopening began, on the heels of three euro auto deals priced towards the end of last week. Those three transactions saw strong investor demand. Indeed, Red & Black Auto Italy 4 achieved the best Italian prints since 2021 below the Class A tranche in late August - all pointing to favourable market conditions and good timing for Santander's latest Golden Bar deal, backed entirely by Italian auto receivables, despite mounting competition from an increasingly crowded post-summer ABS pipeline.
With total Euro primary placement YTD of E77bn on course to beat the post-GFC record full year total of E109bn set in 2025 and with auto collateral hitting an impressive E22bn for 2026 thus far (vs E26.5bn for all of 2025), nothing could be taken for granted – especially with oil approaching $100 / barrel again as the middle east conflict continues. Accordingly, the leads remained slightly cautious on the IPTs set at the beginning of launch week. The IPTs were roughly 6 bps wide of Red & Black Italy's latest triple-A's final pricing and 15-25 bps wider on the tranches equivalent to Classes B & C – IPTs were not provided on Class D...click here to read the full Market Context on Concept ABS.

© 2026 ARC Risk Models Limited

