
9/28/2026

The frantic pace of September has shown only the smallest signs of slowing down. It’s more akin to a modern-day F1 car coasting to conserve energy than slamming on the brakes to avoid the barriers.
There were six fully offered trades this week (plus one retained from Shawbrook). Two of those were in sterling, the remaining four in euros. There’s been a nice mix too, with a BTL RMBS and CMBS from the UK, while in euros there was the usual fare of Consumer and Autos, but from slightly less common regions. There was a French Auto from Stellantis, and then consumer deals from Italy, France and the Netherlands.
The market is clearly becoming less than straight forward. With so much supply, investors are inevitably better armed to be tougher on pricing. That has certainly been evident in the seniors but remains practically non-existent further down the stack with mezz tranches frequently more than three times oversubscribed.
Bankers always say that the seniors are the “bottleneck” –they’re generally more than 80% of the total deal size, meaning deeper pockets are needed to build demand, while the senior investors are typically considering prices against a range of other bonds (which are almost always given better regulatory treatment).
However, that bottleneck is not spread evenly throughout ABS’ universe of products. UK Prime RMBS for example, has had a roughly 5bps-7bps repricing since late 2025. Lloyds’ Permanent 2025-1 from October last year printed at 50bps over Sonia, while its 2026-1 edition in July walked away with 55bps. Since then, none of the four subsequent prime trades have gone tighter.
Similarly, triple-A French consumer looks to have widened out considerably in 2026. This week’s debut from Cofidis (a subsidiary of Credit Mutuel) built good momentum to finish at 73bps, but never looked like getting into the 60s. You may think it’s to be expected for a debut issuer, yet Boursobank was debuting when it priced its May consumer deal at 66bps.
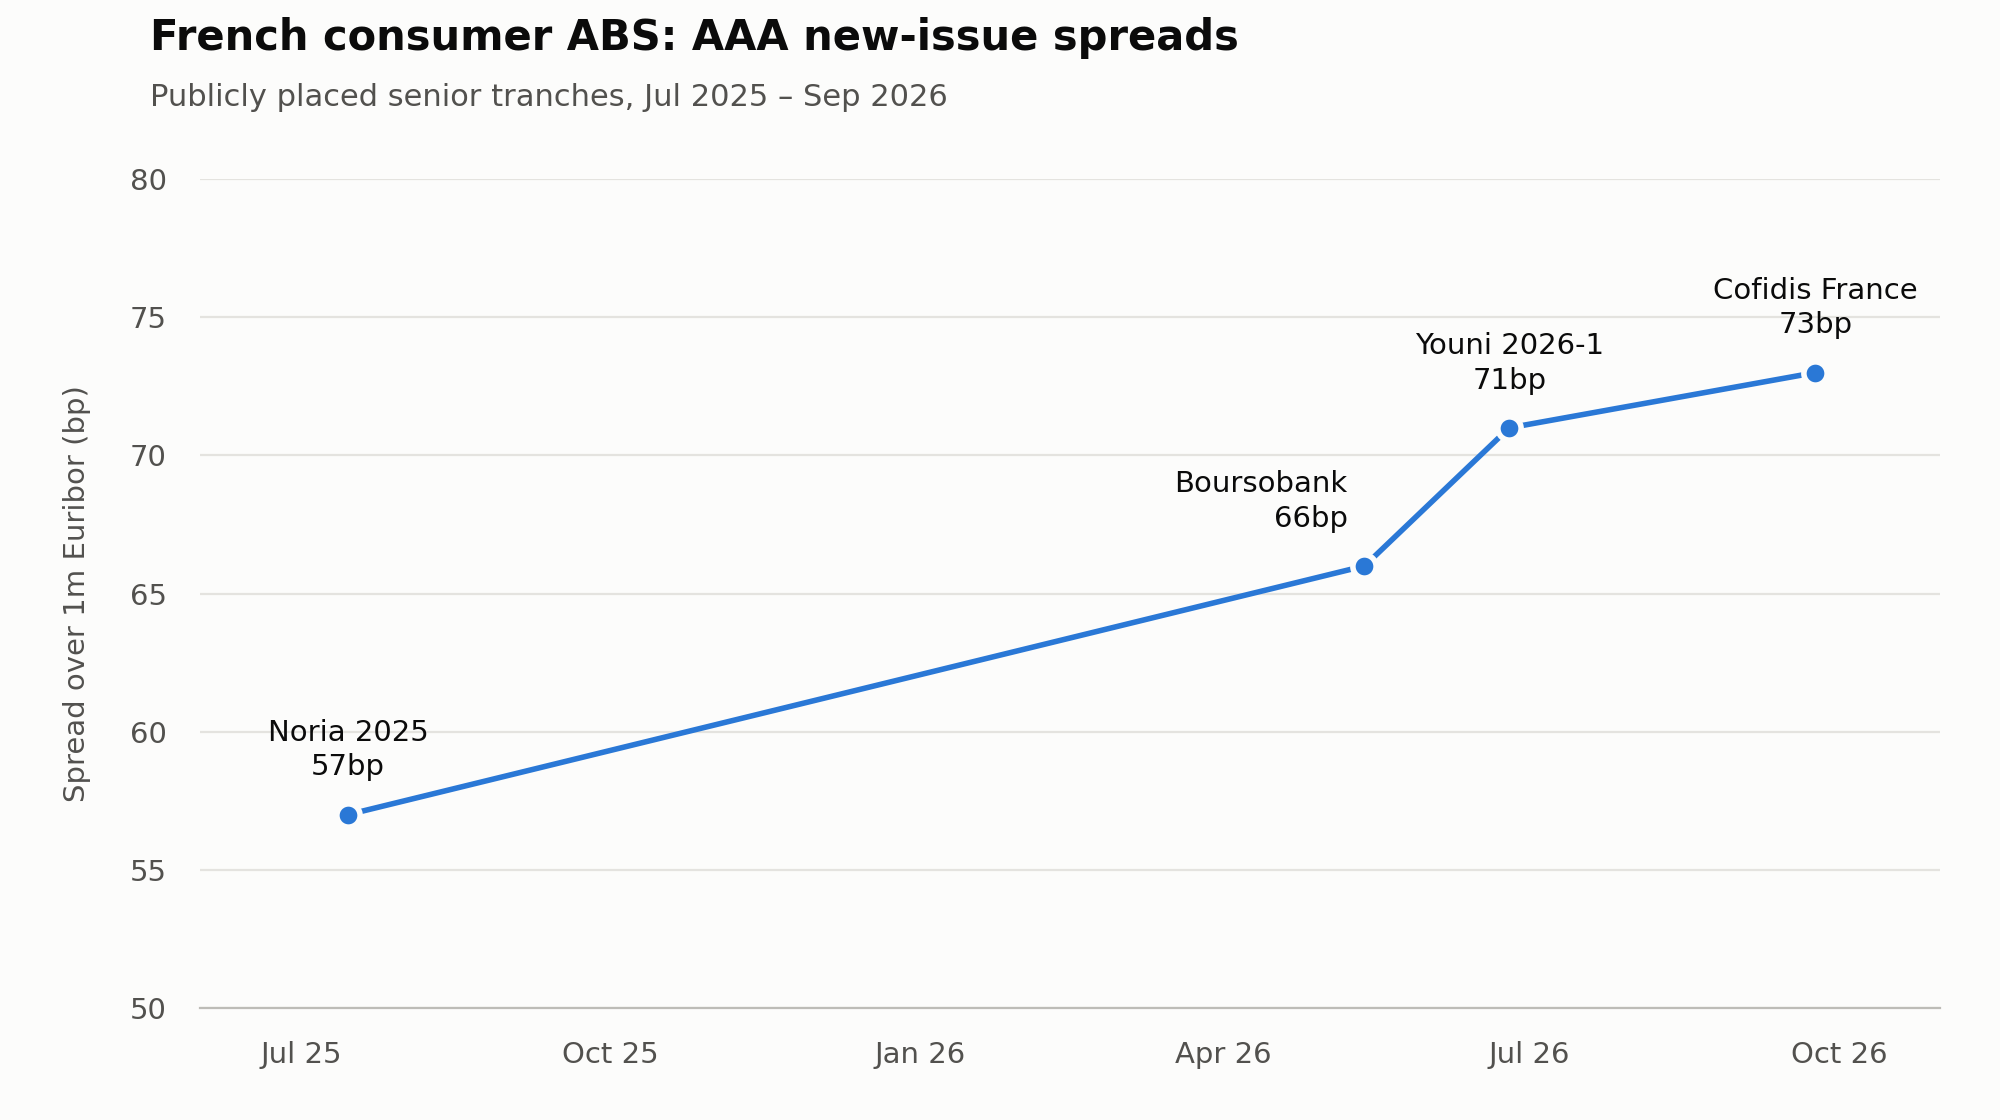
The trend on both French Consumer and UK Prime RMBS makes me wonder whether bank treasuries are the senior investors that are stepping away, as government bonds and covered bonds are also part of their investment decision. Something to keep an eye on.
But despite all that, issuers don’t seem fussed and they’re still coming thick and fast. The pace is slightly gentler with four deals in pipeline, but hopefully, the market can trot along like this well into November.
Paratus has brought another UK rmbs from its BTL / OO programme Braccan. The most recent deal from the brand (Mar-2026) was entirely pre-placed. However, the second Braccan of the year was fully marketed. Certainly, both the Euro and Sterling post summer primary market has seen – and absorbed – unprecedented (since the GFC) paper in less than a month while retaining a solid bid across the stack (so far).
However, with 2026 supply of UK collateral certain to set a post-GFC record – while wider bond market turbulence and ratcheting middle east tensions provide unwanted mood music – investors can't be taken for granted. Indeed, the market isn't quite as strong as it was earlier in the year...click here to read the full overview on Concept ABS.
With c.£32bn sold in 2026 YTD, the sterling ABS primary market has already surged past 2025's full year placement of £25bn and is all but guaranteed to comfortably exceed 2024's post GFC record of £33.6bn. Indeed, Q3's placement of c.£12bn hasn't been bested in nearly 20 years. No fewer than nine transactions featuring UK collateral have priced in September alone (a runrate not matched since the halcyon pre-financial crisis days).
Although Sterling demand was starting to feel a little fatigued before the summer break, investors remain engaged as we approach Q4. However, they are more price sensitive than in H1 of this year. With so much to choose from, investors have become more assertive. Recent rmbs deals have boasted strong coverage across the stack but at pricing levels that are not quite the tightest seen this year. Furthermore, with the middle east conflict threatening a renewed oil crunch and a global bond sell-off (with central bank policy rates very much in focus), accounts need little encouragement to push back.
The leads started out with restrained IPTs of SONIA + high 80s, + low-mid 100s and + mid 100s – all offering tempting pick-ups to where a recent Atlas Funding (Lendco) comparable deal priced its equivalent tranches – at +82, +110 and +130. A book update, a day later, reported coverage of 1.1x, 1.8x and 1.4x on a £406m provisional pool size...click here to read the full Market Context on Concept ABS.

© 2026 ARC Risk Models Limited

